
Build trading integrations on Secure Digital Markets.
Use SDM WebSocket, REST, and FIX APIs to connect market data, order execution, RFQ, trade, balance, and instrument workflows for institutional digital asset trading.
Environments and API keys
Welcome to the SDM API. The websocket API provides the user with access to real-time market data subscription, orders execution and balance information. The REST API provides historical market data.
If you do not have an API key and a signature assigned, you will need to obtain them first. You can do so by using the following method. Email SDM support staff at: tech@sdm.co. You will need separate API Keys for connecting to the sandbox and production environments.
Your websocket endpoint is trade-sandbox.sdm.co in sandbox, and trade.sdm.co in production.
| Environment | WebSocket | REST |
|---|---|---|
| Sandbox | wss://trade-sandbox.sdm.co/ws/v1 | https://trade-sandbox.sdm.co |
| Production | wss://trade.sdm.co/ws/v1 | https://trade.sdm.co |
WebSocket and REST authentication
Websocket connections must be authenticated by signing the request and sending the signature in HTTP headers.
REST requests must be authenticated by signing the request and sending the signature in HTTP headers.
REST Endpoints are available for OHLCV data.
The signature is a base64 encoded sha256 HMAC using the API secret of the following:
Websocket authentication headers
| Header | Description |
|---|---|
| ApiKey | Your SDM API key |
| ApiTimestamp | An ISO-8601 UTC string of the form 2019-02-13T05:17:32.000000Z |
| ApiSign | base64-encoded signature |
REST authentication headers
| Header | Description |
|---|---|
| ApiKey | Your API key |
| ApiTimestamp | An ISO-8601 UTC string of the form 2019-02-13T05:17:32.000000Z |
| ApiSign | base64-encoded signature |
WebSocket signature payload
GET\n<ApiTimestamp>\n<host>\n<path>WebSocket signature payload example
GET\n2019-02-13T05:17:32.000000Z\ntrade-sandbox.sdm.co\n/ws/v1WebSocket Python 2/3 example
# to install websocket lib:
# $ pip install websocket-client
from websocket import create_connection
import datetime
import hmac
import hashlib
import base64
api_key = "<apikey>"
api_secret = "<apisecret>"
utc_now = datetime.datetime.utcnow()
utc_datetime = utc_now.strftime("%Y-%m-%dT%H:%M:%S.000000Z")
host = "<websocket host>" # trade-sandbox.sdm.co, for example
path = "/ws/v1"
params = "\n".join([
"GET",
utc_datetime,
host,
path,
])
hash = hmac.new(
api_secret.encode('ascii'), params.encode('ascii'), hashlib.sha256)
hash.hexdigest()
signature = base64.urlsafe_b64encode(hash.digest()).decode()
header = {
"ApiKey": api_key,
"ApiSign": signature,
"ApiTimestamp": utc_datetime,
}
ws = create_connection("wss://" + host + path, header=header)
while True:
print(ws.recv())REST signature payload
GET\n<ApiTimestamp>\n<host>\n<path>[\nquery][\nbody]query and body should only be included if they are not empty.
REST signature payload example
GET\n2019-02-13T05:17:32.000000Z\ntrade-sandbox.sdm.co\n/v1/symbols/BTC-USD/ohlcv/1DREST Python 2/3 example
# to install requests lib:
# $ pip install requests
import requests
import datetime
import hmac
import hashlib
import base64

api_key = "<apikey>"
api_secret = "<apisecret>"
utc_now = datetime.datetime.utcnow()
utc_datetime = utc_now.strftime("%Y-%m-%dT%H:%M:%S.000000Z")
host = "<host>"  # trade-sandbox.sdm.co, for example
path = "/v1"
query = ""
body = ""
params = [
"GET",
utc_datetime,
host,
path,
]
endpoint = "https://" + host + path

if query:
    endpoint += "?" + query
    params.append(query)
if body:
    params.append(body)

payload = "\n".join(params)
hashvalue = hmac.new(
api_secret.encode('ascii'), payload.encode('ascii'), hashlib.sha256)
hashvalue.hexdigest()
signature = base64.urlsafe_b64encode(hashvalue.digest()).decode()
headers = {
"ApiKey": api_key,
"ApiSign": signature,
"ApiTimestamp": utc_datetime,
}

print(requests.get(url=endpoint, headers=headers))WebSocket protocol
Timestamps: In all API requests, the user has the option to provide a timestamp (ts) in an ISO-8601 UTC string format with microsecond resolution. While optional, we recommend taking advantage of this field, as it will both enable our system to monitor client-server latency and allow certain security features. All system responses are tied to a specific client request. The user should provide a unique reqid (Request ID) on each request, and the system will echo this reqid on the corresponding responses.
The server sends a hello message on a successful connection
After a client connects, the server will send an unsolicited hello message.
Clients issue requests to subscribe to data and execute actions like placing orders. A request should be a JSON message with the following keys:
The server responds to requests with one or more response messages that reference the request by echoing back the reqid field.
There is no limit to how many concurrent websocket connections you're allowed, though this may change in the future. If you expect to have more than ~10 active connections, please contact tech@sdm.co.
Unsolicited hello message
{
  "type": "hello",
  "ts": "2019-10-16T10:41:23.168807Z",
  "session_id": "1109RQ13KXR00"
}Hello fields
| Parameter | Type | Required | Description |
|---|---|---|---|
| type | string | Y | Always "hello". |
| ts | number | Y | An ISO-8601 UTC string of the form 2019-02-13T05:17:32.000000Z |
| session_id | string | Y | A session ID that uniquely identifies this websocket session. |
General request
{
  "reqid": 1,
  "type": "subscribe",
  "streams": [
    {
      "name": "MessageType",
      "Arg1": 1
    }
  ],
  "ts": "2019-02-13T05:17:32.000000Z"
}
General request fields
| Parameter | Type | Required | Description |
|---|---|---|---|
| reqid | number | Y | A number that identifies this request and will be included on responses to this request. |
| type | string | Y | The type of message sent. This document describes all valid message types. |
| ts | number | N | An ISO-8601 UTC string of the form 2019-02-13T05:17:32.000000Z |
reqid cannot be equal to 0.
General response
{
  "reqid": 1,
  "seq": 1,
  "type": "MessageType",
  "action": "Update",
  "data": [
    {
      "Key": "Value"
    }
  ],
  "ts": "2019-02-13T05:17:32.000000Z"
}
General response fields
| Key | Type | Required | Description |
|---|---|---|---|
| reqid | number | Y | A number that relates this response to a request. |
| seq | number | Y | The sequence number for this response per request. seq begins at 1 on the first message with this reqid and increments by one for each message sent on this reqid. |
| type | string | Y | The type of message sent. This document describes all valid message types. |
| tag | string | N | An optional tag from the stream request. |
| ts | number | Y | An ISO-8601 UTC string of the form 2019-02-13T05:17:32.000000Z. |
| initial | bool | N | If this is initial data for a request, the initial flag will be set. |
| action | string | N | "Update" or "Remove" |
| total_count | number | N | The total number of records for this stream. |
If a request requires responses with different types, then multiple responses may have the initial flag set for different types.
seq is for debug purposes only, the client is not required to do any sequencing.
action is either Update or Remove and tells the client if the given entity should be removed or added/updated. The key for a given entity depends on the message type.
In all messages below the described types are encoded as below:
Encoded types
| Type | Encoding |
|---|---|
| datetime | An ISO-8601 UTC string of the form 2019-02-13T05:17:32.000000Z |
| decimal | A string encoded decimal; eg "4.327" represents the decimal 4.327 |
Subscription lifecycle and commands
Send a subscription request to begin a stream of data.
Commands can be submitted via the websocket API.
This is the general structure for sending a command to the websocket API. The type field is the command name, specified as one of the options listed below. The data required for each command is described below. There could be an error response to the command, otherwise any published response data should be consumed via the associated subscription above.
If you request a stream that is paged, the data on the stream will be delivered with a next field populated. If given this field, request the next set of data with the below structure. Response continues as with the original stream.
Subscribe or amend request
| Key | Type | Required | Description |
|---|---|---|---|
| reqid | int | Y | Request ID - will be echoed back in the response structure |
| type | string | Y | "subscribe" for initializing a subscription |
| tag | string | Y | Optional user generated tag to attach to stream data |
| streams | object[] | Y | Streams to subscribe to |
| → name | string | Y | Subscription name |
| → <Subscription Parameters> | --- | ---- | Any required or optional parameters described for the subscription names below |
Amends a subscription request by Request ID. Response structure remains the same, just the content of the data will change per the amendment.
Amend an Existing Stream: Request structure
| Key | Type | Required | Description |
|---|---|---|---|
| reqid | int | Y | Request ID - will be echoed back in the response structure |
| type | string | Y | "subscribe" for initializing a subscription |
| tag | string | Y | Optional user generated tag to attach to stream data |
| streams | object[] | Y | Streams to subscribe to |
| → name | string | Y | Subscription name |
| → <Subscription Parameters> | --- | ---- | Any required or optional parameters described for the subscription names below |
Stream update
| Key | Type | Required | Description |
|---|---|---|---|
| reqid | int | Y | Echoed back request ID |
| type | string | Y | Echoed back subscription name to define the type of the data |
| seq | int | Y | Incrementing sequence number of messages for request ID starting with 1 |
| initial | boolean | Y | Flag to indicate if this message is the initial state of the stream |
| ts | datetime | Y | Timestamp of message publication |
| data | object[] | Y | List of response data structured per subscription type below |
| next | string | N | If paging, tag for next page of data |
Page request
| Key | Type | Required | Description |
|---|---|---|---|
| reqid | int | Y | The request ID to continue the page, must match the original request ID |
| type | string | Y | "page" for continuing the paged stream |
| data | object[] | Y | Stream request data to continue |
| → name | string | Y | Subscription name to continue the page |
| → after | string | Y | Delivered next value from the paged stream payload |
Cancels an existing stream by Request ID. No response, unless there is an error. Stream will just stop.
Cancel an Existing Stream: Request structure
| Key | Type | Required | Description |
|---|---|---|---|
| reqid | int | Y | Request ID to cancel |
| type | string | Y | "cancel" for cancelling the subscription |
Command envelope
| Key | Type | Required | Description |
|---|---|---|---|
| type | string | Y | The type of the command to send |
| data | object[] | Y | Any requisite data that needs to be submitted along with the command |
Security stream
SDM maintains a security master which contains up-to-date information about the securities supported over API that are available to trade. The user should use the below streams when subscribing to the Security Master data.
Request for stream of available securities for trading. On initial request, a snapshot of all available securities is provided. All subsequent messages are deltas to the securities snapshot.
SecuritySecurity subscription
{
  "reqid": 2,
  "type": "subscribe",
  "streams": [
    {
      "name": "Security"
    }
  ]
}
Security response
{
  "reqid": 2,
  "type": "Security",
  "ts": "2021-09-14T22:11:47.512168Z",
  "initial": true,
  "seqNum": 1,
  "data": [
    {
      "Timestamp": "2021-09-14T22:11:47.512168Z",
      "UpdateAction": "Update",
      "SecurityID": 2,
      "Symbol": "ETH-USD",
      "MinPriceIncrement": "0.01",
      "MinSizeIncrement": "0.00000001",
      "MinAmtIncrement": "0.01",
      "MinimumSize": "0.00000001",
      "MaximumSize": "10000000",
      "QuoteCurrency": "USD",
      "BaseCurrency": "ETH",
      "DefaultPriceIncrement": "0.01",
      "DefaultSizeIncrement": "0.0001",
      "PriceDisplaySpec": "M.m",
      "SizeDisplaySpec": "M.m",
      "NormalSize": "2",
      "ProductType": "Spot",
      "PositionCurrency": "ETH",
      "SettlementCurrency": "USD",
      "NotionalMultiplier": "1",
      "SizeBuckets": [
        {
          "Size": "0"
        }
      ],
      "DisplaySymbol": "ETH-USD",
      "Description": "Ethereum/U.S. Dollar"
    }
  ]
}
Subscription parameters
| Key | Type | Required | Description |
|---|---|---|---|
| Symbols | []string | N | Optional list of symbols to filter the subscription on |
Response fields
| Key | Type | Required | Description |
|---|---|---|---|
| Timestamp | datetime | Y | Timestamp of message publication |
| UpdateAction | string | Y | Update or Remove where the latter indicates the Security is no longer available |
| SecurityID | string | Y | System ID for Security - for information only |
| Symbol | string | Y | Symbol for security |
| MinPriceIncrement | decimal | Y | Minimum Price Increment for Security |
| MinSizeIncrement | decimal | Y | Minimum Size Increment for Security. This increment is used to validate orders and RFQS expressed in base currency of the security. |
| MinAmtIncrement | decimal | N | Minimum Amount Increment for Security. This increment is used to validate orders and RFQS expressed in quote currency of the security. |
| MinimumSize | decimal | Y | Minimum Size for an Order on this Security |
| MaximumSize | decimal | N | Maximum Size for an Order on this Security |
| QuoteCurrency | string | Y | Currency in which the Security is quoted |
| BaseCurrency | string | Y | Base currency for the Security |
| EndTime | datetime | N | Date this security was Disabled |
| DefaultPriceIncrement | decimal | Y | Default price increment used in all Market Data and Orders |
| DefaultSizeIncrement | decimal | Y | Default size increment used in all Market Data and Orders |
| PriceDisplaySpec | string | Y | String specification describing the price display |
| NormalSize | decimal | N | Normal size of Security |
| ProductType | string | N | Product type of Security |
| PositionCurrency | string | Y | Currency in which any position on this Security is tracked |
| SettlementCurrency | string | N | Currency in which any settlement on thes Security is negotiated |
| NotionalMultiplier | decimal | N | Notional Multiplier of Security |
| Expiration | decimal | N | Expiration of Security |
| SizeBuckets | []decimal | Y | Default array of Size Buckets for Market Data Snapshot Streams |
| DisplaySymbol | string | Y | Display symbol for Security |
| Description | string | Y | Description of Security |
Currency stream
Request for stream of available currencies used within trading. On initial request, a snapshot of all available currencies is provided. All subsequent messages are deltas to the currency snapshot.
CurrencyCurrency subscription
{
  "reqid": 3,
  "type": "subscribe",
  "streams": [
    {
      "name": "Currency"
    }
  ]
}
Currency response
{
  "reqid": 3,
  "type": "Currency",
  "ts": "2021-09-14T22:11:47.512168Z",
  "initial": true,
  "seqNum": 1,
  "data": [
    {
      "Timestamp": "2020-09-30T17:56:08.552227Z",
      "UpdateAction": "Update",
      "CurrencyID": 2,
      "Symbol": "USD",
      "MinIncrement": "0.01",
      "DefaultIncrement": "0.01",
      "Description": "U.S. Dollar"
    },
    {
      "Timestamp": "2020-05-13T13:24:58.983054Z",
      "UpdateAction": "Update",
      "CurrencyID": 17,
      "Symbol": "ETH",
      "MinIncrement": "0.00000001",
      "DefaultIncrement": "0.0001",
      "Description": "Ethereum"
    }
  ]
}
Subscription parameters
| Key | Type | Required | Description |
|---|---|---|---|
| Symbols | []string | N | Optional list of currency symbols to filter the subscription on |
Response fields
| Key | Type | Required | Description |
|---|---|---|---|
| Timestamp | datetime | Y | Timestamp of message publication |
| CurrencyID | string | Y | System ID for Currency - for information only |
| Symbol | string | Y | Symbol for currency |
| MinIncrement | decimal | Y | Minimum increment for Currency |
| DefaultIncrement | decimal | Y | Default increment used in all Market Data and Orders |
| Description | string | Y | Description of Security |
MarketDataSnapshot stream
This section outlines how to subscribe to market data via the SDM API.
Request stream of MarketDataSnapshot messages. To stream security pricing.
MarketDataSnapshotMarket data subscription
{
  "reqid": 5,
  "type": "subscribe",
  "streams": [
    {
      "name": "MarketDataSnapshot",
      "Symbol": "BTC-USD"
    }
  ]
}
Market data response
{
  "reqid": 5,
  "type": "MarketDataSnapshot",
  "ts": "2021-09-14T22:20:49.862930Z",
  "initial": true,
  "seqNum": 1,
  "data": [
    {
      "Timestamp": "2021-09-14T22:20:49.860957Z",
      "Symbol": "BTC-USD",
      "Status": "Online",
      "Bids": [
        {
          "Price": "46817.27965000",
          "Size": "1.00000000"
        },
        {
          "Price": "46816.08025000",
          "Size": "2.00000000"
        }
      ],
      "Offers": [
        {
          "Price": "46868.59755873",
          "Size": "1.00000000"
        },
        {
          "Price": "46870.33345500",
          "Size": "2.00000000"
        }
      ]
    }
  ]
}
Subscription parameters
| Key | Type | Required | Description |
|---|---|---|---|
| Symbol | string | Y | Security to request |
| Throttle | string | N | An optional throttle duration for updates, defaults to configured MinMarketDataThrottle. A throttle is specified by a time duration + units. For example: "300ms", "500us". Valid time units are "ns", "us", "ms", "s". |
| PriceIncrement | decimal | N | Price increment for levels to enable price bucketing |
| Depth | decimal | N | Maximum number of bid / offer levels to stream prices for |
| SizeBuckets | []decimal | N | A list of sizes to return price levels for; defaults to configured Security SizeBuckets |
Response fields
| Key | Type | Required | Description |
|---|---|---|---|
| Timestamp | datetime | Y | Timestamp of update |
| Symbol | string | Y | Security for update |
| Status | string | Y | Status of update; Online or Offline |
| Bids | object[] | Y | Full list of Bids |
| → Price | decimal | Y | Limit price of the level. |
| → Size | decimal | Y | Size on this level. |
| Offers | object[] | Y | Full list of Offers |
| → Price | decimal | Y | Limit price of the level. |
| → Size | decimal | Y | Size on this level. |
CurrencyConversion stream
Request for stream of currency conversion rates.
CurrencyConversionConversion subscription
{
  "reqid": 4,
  "type": "subscribe",
  "streams": [
    {
      "name": "CurrencyConversion",
      "EquivalentCurrency": "USD",
      "Currencies": [
        "BTC",
        "ETH",
        "BCH-USD"
      ],
      "Throttle": "15s",
      "Tolerance": "0.0002"
    }
  ]
}
Conversion response
{
  "reqid": 4,
  "type": "CurrencyConversion",
  "ts": "2021-09-14T22:16:18.604996Z",
  "initial": true,
  "seqNum": 1,
  "data": [
    {
      "Timestamp": "2021-09-14T22:16:18.604674Z",
      "EquivalentCurrency": "USD",
      "Currency": "ETH",
      "Rate": "3368.16",
      "Status": "Online",
      "ConversionPath": "(ETH-USD)"
    },
    {
      "Timestamp": "2021-09-14T22:16:18.604674Z",
      "EquivalentCurrency": "USD",
      "Currency": "BTC",
      "Rate": "46841.35",
      "Status": "Online",
      "ConversionPath": "(BTC-USD)"
    },
    {
      "Timestamp": "2021-09-14T22:16:18.604674Z",
      "EquivalentCurrency": "USD",
      "Currency": "BCH-USD",
      "Rate": "639.530000000000",
      "Status": "Online",
      "ConversionPath": "(BCH-USD)"
    }
  ]
}
Subscription parameters
| Key | Type | Required | Description |
|---|---|---|---|
| EquivalentCurrency | string | Y | Quote currency to base the conversion rates on |
| Currencies | []string | N | List of currencies and securities to generate conversion rates for; defaults to all available currencies |
| Throttle | string | N | Optional throttle interval for conversion rate updates. Minimal / default value: 10s |
| Tolerance | decimal | N | Optional param to indicate what conversation rate percent change should trigger sending out an update. Minimal / default value: 0.0001 which means 1 bps |
Response fields
| Key | Type | Required | Description |
|---|---|---|---|
| Timestamp | datetime | Y | Timestamp of message publication |
| EquivalentCurrency | string | Y | Currency symbol for equivalent currency |
| Currency | string | Y | Currency symbol for base currency on conversion |
| Rate | decimal | Y | Currency conversion rate |
Order workflow and supported strategies
This section outlines how to send orders using the SDM API. To send orders, first subscribe to the ExecutionReport stream. All order responses and updates are sent as ExecutionReport 's'. Send requests with the NewOrderSingle, OrderCancelRequest, OrderCancelReplaceRequest, and OrderControlRequest messages.
To generate a ClOrdID, we recommend using a UUID4 or another globally unique identifier. ClOrdID must be unique daily and among any open order and must be less than 36 characters.
The orders API roughly follows the same semantics as the FIX Protocol, though with some notable differences, see Order State Change Matrices for more details.
A typical trading strategy would do the following:
- Subscribe to MarketDataSnapshot for the relevant securities
- Subscribe to ExecutionReport with StartDate of the Timestamp of the last ExecutionReport processed to recover order state.
- Subscribe to Trade with StartDate of the Timestamp of the last Trade processed to recover any missed trades.
- Maintain a map of (OrderID , last received ExecutionReport ) for open orders.
- Maintain a set of ClOrdID for each pending request.
- To submit an order, first generate a new ClOrdID (see instructions below). Send a NewOrderSingle specifying the ClOrdID , Side , Price , OrderQty , Strategy , etc. for that request.
- The response for the request will be received on the ExecutionReport stream with the ClOrdID being the ClOrdID specified on the NewOrderSingle . If the order is accepted (ExecType=PendingNew ), then add this order to the set of open orders.
- To cancel or modify the open order, generate a new ClOrdID and send an OrderCancelRequest or OrderCancelReplaceRequest specifying the the ClOrdID , OrigClOrdID from the previous successful request, and remaining parameters.
- Fills will be received as ExecutionReport with ExecType=Trade .
A schedule-based algorithm that divides an order into suborders (clips) and submits them at equal, user defined intervals.
SteadyPace parameters
| Parameter | Type | Required | Description |
|---|---|---|---|
| ClipSize | Qty | Y | A quantity (subset of the total order size) to send on each execution of the schedule. |
| ClipInterval | string | Y | Time interval between individual clips specified as an interval string. |
| StartTime | string | N | Time at which this order will activate and begin sending orders. An ISO-8601 UTC string of the form 2019-02-13T05:17:32.000000Z |
| EndTime | string | N | Optional expire time for the order. An ISO-8601 UTC string of the form 2019-02- 13T05:17:32.000000Z |
| Variance | decimal | N | Optional degree of randomization for clip sizes. |
An interval or duration string is a possibly signed sequence of decimal numbers, each with optional fraction and a unit suffix, such as 300ms or 2h45m. Valid time units are ns, us (or µs), ms, s, m, h. A variance of 0.1 (implying a variance of 10%) for a clip size of 1.0 would result in clips ranging between 0.9 and 1.1.
StopLimit parameters
| Parameter | Type | Required | Description |
|---|---|---|---|
| TriggerPrice | Price | Y | The price that must be met to trigger execution of the order with the configured limit price. |
| EndTime | string | N | Optional expire time for the order. An ISO-8601 UTC string of the form 2019-02- 13T05:17:32.000000Z |
This strategy will only place the order once the specified stop price has been met. For a Buy StopLimit order, the stop price must be above the current market price. For a Sell StopLimit order, the stop price must be below the current market price.
Order stream
Request stream of Order updates.
An Order update having a data field containing an array that has a similar structure to ExecutionReport
OrderOrder subscription
{
  "reqid": 7,
  "type": "subscribe",
  "streams": [
    {
      "name": "Order"
    }
  ]
}
Order response
{
  "reqid": 7,
  "type": "Order",
  "ts": "2021-09-14T22:26:44.518538Z",
  "initial": false,
  "seqNum": 3,
  "data": [
    {
      "Timestamp": "2021-09-14T22:26:44.505519Z",
      "Symbol": "BTC-USD",
      "OrderID": "b35b1c3b-a304-4224-919f-9db1319de188",
      "ClOrdID": "d7635e40-15aa-11ec-b0a2-2554a9e1e7a4",
      "SubmitTime": "2021-09-14T22:26:44.457050Z",
      "ExecID": "c73fcf77-aaa1-46e7-9260-f625d6416646",
      "Side": "Buy",
      "ExecType": "New",
      "OrdStatus": "New",
      "OrderQty": "0.10000000",
      "OrdType": "Market",
      "Currency": "BTC",
      "LeavesQty": "0.10000000",
      "CumQty": "0",
      "AvgPx": "0",
      "TimeInForce": "FillOrKill",
      "LastPx": "0",
      "LastQty": "0",
      "LastAmt": "0",
      "LastFee": "0",
      "CumAmt": "0",
      "DecisionStatus": "Active",
      "AmountCurrency": "USD",
      "CustomerUser": "tom@company.com",
      "Parameters": {
        "ErrorAction": "Pause"
      }
    }
  ]
}
Subscription parameters
| Key | Type | Required | Description |
|---|---|---|---|
| StartDate | string | N | If provided, the subscription will return orders that were submitted after this time. An ISO-8601 UTC string of the form 2019-02-13T05:17:32.000000Z |
| EndDate | string | N | If provided, the subscription will return orders that were submitted before this time. An ISO-8601 UTC string of the form 2019-02-13T05:17:32.000000Z |
| Symbol | string | N | If provided, Symbol of the security to get the orders for |
| Statuses | string[] | N | If provided, comma-separated Statuses of orders to include e.g. New,Filled |
| OrderID | string | N | If provided, filter by OrderID |
| RFQID | string | N | If provided, filter by RFQID |
ExecutionReport stream
Request stream of Execution Reports.
ExecutionReportExecution report subscription
{
  "reqid": 6,
  "type": "subscribe",
  "streams": [
    {
      "name": "ExecutionReport"
    }
  ]
}
Execution report response
{
  "reqid": 6,
  "type": "ExecutionReport",
  "ts": "2021-09-14T22:23:11.920903Z",
  "initial": false,
  "seqNum": 2,
  "data": [
    {
      "Timestamp": "2021-09-14T22:23:11.903074Z",
      "Symbol": "BTC-USD",
      "OrderID": "1b6b882b-e2fc-4774-ad2d-9db4df536f29",
      "ClOrdID": "58b9adb0-15aa-11ec-b0a2-2554a9e1e7a4",
      "SubmitTime": "2021-09-14T22:23:11.903074Z",
      "ExecID": "4b423f54-4a54-4679-9ee7-1f5f417ec5f5",
      "Side": "Buy",
      "TransactTime": "2021-09-14T22:23:11.883000Z",
      "ExecType": "PendingNew",
      "OrdStatus": "PendingNew",
      "OrderQty": "0.20000000",
      "OrdType": "Market",
      "Currency": "BTC",
      "LeavesQty": "0.20000000",
      "CumQty": "0",
      "AvgPx": "0",
      "TimeInForce": "FillOrKill",
      "LastPx": "0",
      "LastQty": "0",
      "LastAmt": "0",
      "LastFee": "0",
      "CumAmt": "0",
      "AmountCurrency": "USD",
      "CustomerUser": "tom@company.com",
      "Parameters": {
        "ErrorAction": "Pause"
      }
    }
  ]
}
Subscription parameters
| Key | Type | Required | Description |
|---|---|---|---|
| StartDate | string | N | If provided, the subscription will return execution reports that were published at or after this time. An ISO-8601 UTC string of the form 2019-02-13T05:17:32.000000Z |
| EndDate | string | N | If provided, the subscription will return execution reports that were published before this time. An ISO-8601 UTC string of the form 2019-02-13T05:17:32.000000Z |
| Symbol | string | N | If provided, Symbol of the security to get the executions for |
| Statuses | string[] | N | If provided, comma-separated statuses of orders to include e.g. New,Filled |
| OrderID | string | N | If provided, filter by OrderID |
| RFQID | string | N | If provided, filter by RFQID |
Response fields
| Key | Type | Required | Description |
|---|---|---|---|
| Timestamp | datetime | Y | Timestamp of the message |
| Symbol | string | Y | Symbol of the order security |
| OrderID | string | Y | Server assigned Order ID, will be a UUID |
| ClOrdID | string | Y | Client assigned Order ID for the last request |
| OrigClOrdID | string | Y | Original client assigned |
| SubmitTime | datetime | Y | Time of original order submission |
| ExecID | string | Y | Server assigned ID of this update, will be a UUID |
| Side | string | Y | "Buy" or "Sell" |
| TransactTime | datetime | N | An ISO-8601 UTC string of the form 2019-02-13T05:17:32.000000Z |
| ExecType | string | Y | Describes the specific execution (e.g. Pending Cancel) while OrdStatus will always identify the current order status (e.g. Partially Filled). Valid values: New, Trade, Canceled, Replaced, PendingCancel, Stopped, Rejected, PendingNew, Restated, PendingReplace, CancelRejected, ReplaceRejected, PendingResume, Resumed, PendingPause, Paused, Triggered, Started |
| OrdStatus | string | Y | Identifies current status of order. Valid values: New, PartiallyFilled, Filled, Canceled, PendingCancel, Rejected, PendingNew, PendingReplace. |
| OrderQty | decimal | Y | Order quantity |
| OrdType | string | Y | Order type. Valid values: Market, Limit, or RFQ |
| Price | decimal | N | Order limit price, required when OrdType=Limit |
| Currency | string | Y | Currency of Quantity |
| LeavesQty | decimal | Y | Quantity open for further execution. If the OrdStatus is Canceled or Rejected (in which case the order is no longer active) then LeavesQty could be 0, otherwise LeavesQty = OrderQty – CumQty |
| CumQty | decimal | Y | Total quantity filled. Always in Currency units (BTC of a BTC-USD order) |
| AvgPx | decimal | N | Average filled price of the order. Only valid if CumQty > 0. Does not include fees |
| TimeInForce | string | Y | Specifies how long the order remains in effect. Valid values: GoodTillCancel, FillAndKill, or FillOrKill |
| LastPx | decimal | N | Last price, specified when ExecType=Trade |
| LastQty | decimal | N | Last qty, specified when ExecType=Trade |
| LastAmt | decimal | N | Last amount, specified when ExecType=Trade |
| LastFee | decimal | N | Last fee, specified when ExecType=Trade |
| LastFeeCurency | string | N | Last fee currency, specified when ExecType=Trade. Note this may be different from the cumulative fee |
| CumAmt | decimal | N | Total amount filled. Always in Amount currency (USD of a BTC-USD order) |
| FeeCurency | string | N | Cumulative fee currency |
| OrdRejReason | string | N | Order reject reason, specified when ExecType=Rejected. Valid values: UnknownSymbol, OrderExceedsLimit, TooLateToEnter, UnknownOrder, DuplicateOrder, StaleRequest, InternalError, BrokerOption, RateLimit, ForceCancel, ImmediateOrderDidNotCross, PostOnlyOrderWouldCross, InvalidStrategy, QuoteRequestTimeout, QuoteExpired |
| CxlRejReason | string | N | Cancel reject reason, specified when ExecType=CancelRejected or ExecType=ReplaceRejected. Valid values: UnknownOrder, Broker, OrderAlreadyInPendingCancelOrPendingReplaceStatus, DuplicateClOrdID, TooLateToCancel, StaleRequest, RateLimit, InvalidStrategy, Other |
| QuoteID | string | N | Server assigned QuoteID for RFQ Orders |
| AmountCurrency | string | Y | Currency of Amount |
| SessionID | string | Y | SessionID that submitted this order |
| CancelSessionID | string | N | If specified, the order will be cancelled when this session is closed |
| Strategy | string | N | Name of the Order Strategy to use |
| RFQID | string | N | Server assigned RFQID for RFQ Orders |
| AllowedSlippage | decimal | N | AllowedSlippage in absolute value (ie. 0.001 = 10 bps) if specified on order |
| Text | string | N | Human readable error message |
| CustomerUser | string | N | The customer user associated with this execution report. |
NewOrderSingle command
Command used to submit a new order either against any provided liquidity or an open RFQ. Results of this command will be visible in the Order , ExecutionReport and Trade streams which will track the lifecycle of the order.
NewOrderSingleSubmit NewOrderSingle
{
  "reqid": 12,
  "type": "NewOrderSingle",
  "data": [
    {
      "Symbol": "BTC-USD",
      "ClOrdID": "4d489920-15da-11ec-b5e7-7f4881f01b7d",
      "Side": "Buy",
      "TransactTime": "2021-09-15T04:06:28.530000Z",
      "OrderQty": "0.5",
      "OrdType": "Limit",
      "Price": "43000",
      "Currency": "BTC",
      "TimeInForce": "GoodTillCancel",
      "Strategy": "Limit",
      "Parameters": {
        "ErrorAction": "Pause"
      }
    }
  ]
}
Command data
| Key | Type | Required | Description |
|---|---|---|---|
| Timestamp | datetime | N | Timestamp of the message |
| Symbol | string | Y | Symbol of the security to submit an order on |
| ClOrdID | string | Y | Unique Client Order ID for this request, usually a UUID |
| Side | string | Y | Side of the order, either Buy or Sell |
| OrderQty | decimal | Y | Order quantity in units of Currency |
| OrdType | string | Y | Order type. Valid values: Market, Limit, or RFQ |
| Price | decimal | N | Order limit price, required for Limit orders |
| TransactTime | datetime | N | An ISO-8601 UTC string of the form 2019-02-13T05:17:32.000000Z |
| Currency | string | N | The currency that the quantity is specified in. If not specified, defaults to the base currency for the symbol |
| QuoteID | string | N | Optional QuoteID to trade on. Must be specified when OrdType=RFQ |
| RFQID | string | N | Optional RFQID to trade on. Must be specified when OrdType=RFQ |
| TimeInForce | string | Y | Specifies how long the order remains in effect. Valid values: GoodTillCancel, FillAndKill, or FillOrKill |
| Strategy | string | N | Optional order strategy to use. For algorithmic orders SteadyPace, `StopLimit' are supported |
| AllowedSlippage | decimal | N | Optional allowed price slippage for Limit order placed against RFQ |
| Parameters | object | N | Optional order strategy parameters |
OrderCancelRequest command
Command used to cancel an open order. Results of this command will be visible in the Order and ExecutionReport streams.
OrderCancelRequestSubmit OrderCancelRequest
{
  "reqid": 13,
  "type": "OrderCancelRequest",
  "data": [
    {
      "ClOrdID": "c0be17e0-15da-11ec-b5e7-7f4881f01b7d",
      "OrderID": "16a55364-4248-4575-aa0b-dddd3f694ca3",
      "TransactTime": "2021-09-15T04:09:42.238000Z"
    }
  ]
}
Command data
| Key | Type | Required | Description |
|---|---|---|---|
| Timestamp | datetime | N | Timestamp of the message |
| Symbol | string | Y | Symbol of the security to submit an order on |
| ClOrdID | string | Y | Unique Client Order ID for this request, usually a UUID |
| OrigClOrdID | string | N | Client Order ID of the order to cancel, one of OrderID, OrigClOrdID is required |
| OrderID | string | N | Order ID of the order to cancel, one of OrderID, OrigClOrdID is required |
| TransactTime | datetime | Y | An ISO-8601 UTC string of the form 2019-02-13T05:17:32.000000Z |
OrderCancelReplaceRequest command
Command used to modify an open order. Results of this command will be visible in the Order and ExecutionReport streams.
OrderCancelReplaceRequestSubmit OrderCancelReplaceRequest
{
  "reqid": 14,
  "type": "OrderCancelReplaceRequest",
  "data": [
    {
      "Price": "44000",
      "Symbol": "BTC-USD",
      "OrderID": "16a55364-4248-4575-aa0b-dddd3f694ca3",
      "ClOrdID": "b5e52570-15da-11ec-b5e7-7f4881f01b7d",
      "TransactTime": "2021-09-15T04:09:24.039000Z",
      "OrderQty": "0.5",
      "Parameters": {
        "ErrorAction": "Pause"
      }
    }
  ]
}
Command data
| Key | Type | Required | Description |
|---|---|---|---|
| Timestamp | datetime | N | Timestamp of the message |
| Symbol | string | Y | Symbol of the security to submit an order on |
| ClOrdID | string | Y | Unique Client Order ID for this request, usually a UUID |
| OrigClOrdID | string | N | Client Order ID of the order to cancel, one of OrderID, OrigClOrdID is required |
| OrderID | string | N | Order ID of the order to cancel, one of OrderID, OrigClOrdID is required |
| OrderQty | decimal | Y | Order quantity in units of Currency |
| Price | decimal | N | Order limit price, required for Limit orders |
| TransactTime | datetime | Y | An ISO-8601 UTC string of the form 2019-02-13T05:17:32.000000Z |
| Strategy | string | N | Optional order strategy to use. For algorithmic orders Pegged, TWAP, FullAmount, TimeSliced, and SteadyPace are supported |
| EndTime | datetime | N | Optional expire time for the order. An ISO-8601 UTC string of the form 2019-02- 13T05:17:32.000000Z |
| Parameters | object | N | Optional order strategy parameters |
OrderControlRequest command
Command used to Pause or Resume an open order. Results of this command will be visible in the Order and ExecutionReport streams.
OrderControlRequestSubmit OrderControlRequest
{
  "reqid": 17,
  "type": "OrderControlRequest",
  "data": [
    {
      "ClOrdID": "9eb07120-15da-11ec-b5e7-7f4881f01b7d",
      "OrderID": "16a55364-4248-4575-aa0b-dddd3f694ca3",
      "Action": "Pause"
    }
  ]
}
Command data
| Key | Type | Required | Description |
|---|---|---|---|
| Timestamp | datetime | N | Timestamp of the message |
| ClOrdID | string | Y | Unique Client Order ID for this request, usually a UUID |
| OrigClOrdID | string | N | Client Order ID of the order to submit the control request for, one of OrderID, OrigClOrdID is required |
| OrderID | string | N | Order ID of the order to submit the control request for, one of OrderID, OrigClOrdID is required |
| TransactTime | datetime | Y | An ISO-8601 UTC string of the form 2019-02-13T05:17:32.000000Z |
| Action | string | Y | Action to apply on the order, either Pause or Resume |
WebSocket order state change matrices
The orders API follows FIX 4.4 semantics closely. The main difference is that instead of sending separate OrderCancelReject messages, two extra ExecType are supported: CancelRejected and ReplaceRejected. The order state change matrices below are heavily inspired by the FIX documentation.
Filled order
| Time | Request (ClOrdID,OrigClOrdID) | Response (ClOrdID,OrigClOrdID) | ExecType | OrdStatus | OrderQty | CumQty | LeavesQty | LastQty | Comment |
|---|---|---|---|---|---|---|---|---|---|
| 1 | NewOrderSingle(A) | 10 | |||||||
| 2 | ExecutionReport(A) | PendingNew | PendingNew | 10 | 0 | 10 | |||
| 3 | ExecutionReport(A) | Rejected | Rejected | 10 | 0 | 10 | If order is rejected | ||
| 3 | ExecutionReport(A) | New | New | 10 | 0 | 10 | |||
| 4 | ExecutionReport(A) | Trade | PartiallyFilled | 10 | 2 | 8 | 2 | ||
| 5 | ExecutionReport(A) | Trade | PartiallyFilled | 10 | 3 | 7 | 1 | ||
| 6 | ExecutionReport(A) | Trade | Filled | 10 | 10 | 0 | 7 |
Orders with CumQty > 0 will receive an Execution Report that will have CumQty for the filled size of the order. Orders that are partially filled and canceled will receive an ExecutionReport with a terminal state (Canceled) and a CumQty > 0
Canceled order
| Time | Request (ClOrdID,OrigClOrdID) | Response (ClOrdID,OrigClOrdID) | ExecType | OrdStatus | OrderQty | CumQty | LeavesQty | LastQty | Comment |
|---|---|---|---|---|---|---|---|---|---|
| 1 | NewOrderSingle(A) | 10 | |||||||
| 2 | ExecutionReport(A) | PendingNew | PendingNew | 10 | 0 | 10 | |||
| 3 | ExecutionReport(A) | Rejected | Rejected | 10 | 0 | 10 | If order is rejected | ||
| 3 | ExecutionReport(A) | New | New | 10 | 0 | 10 | |||
| 4 | OrderCancelRequest(B,A) | ||||||||
| 5 | ExecutionReport(B,A) | CancelRejected | New | 10 | 0 | 10 | If cancel is rejected | ||
| 5 | ExecutionReport(B,A) | PendingCancel | PendingCancel | 10 | 0 | 10 | |||
| 6 | ExecutionReport(B,A) | CancelRejected | New | 10 | 0 | 10 | If cancel is rejected | ||
| 7 | ExecutionReport(B,A) | Canceled | Canceled | 10 | 0 | 0 |
Replace to increase quantity
| Time | Request (ClOrdID,OrigClOrdID) | Response (ClOrdID,OrigClOrdID) | ExecType | OrdStatus | OrderQty | CumQty | LeavesQty | LastQty | Comment |
|---|---|---|---|---|---|---|---|---|---|
| 1 | NewOrderSingle(A) | 10 | |||||||
| 2 | ExecutionReport(A) | PendingNew | PendingNew | 10 | 0 | 10 | |||
| 3 | ExecutionReport(A) | New | New | 10 | 0 | 10 | |||
| 4 | OrderCancelReplaceRequest(B,A) | 11 | |||||||
| 5 | ExecutionReport(B,A) | ReplaceRejected | New | 10 | 0 | 10 | If replace is rejected | ||
| 5 | ExecutionReport(B,A) | PendingReplace | PendingReplace | 10 | 0 | 10 | |||
| 6 | ExecutionReport(B,A) | CancelRejected | New | 10 | 0 | 10 | If replace is rejected | ||
| 7 | ExecutionReport(B,A) | Replaced | New | 11 | 0 | 0 | |||
| 8 | ExecutionReport(B) | Trade | PartiallyFilled | 11 | 1 | 10 | 1 |
Replace during fill
| Time | Request (ClOrdID,OrigClOrdID) | Response (ClOrdID,OrigClOrdID) | ExecType | OrdStatus | OrderQty | CumQty | LeavesQty | LastQty | Comment |
|---|---|---|---|---|---|---|---|---|---|
| 1 | NewOrderSingle(A) | 10 | |||||||
| 2 | ExecutionReport(A) | PendingNew | PendingNew | 10 | 0 | 10 | |||
| 3 | ExecutionReport(A) | New | New | 10 | 0 | 10 | |||
| 4 | OrderCancelReplaceRequest(B,A) | 8 | |||||||
| 5 | ExecutionReport(A) | Trade | PartiallyFilled | 10 | 1 | 9 | 1 | Fill before replace is received | |
| 6 | ExecutionReport(B,A) | PendingReplace | PendingReplace | 10 | 1 | 9 | |||
| 7 | ExecutionReport(A) | Trade | PendingReplace | 10 | 3 | 7 | 2 | Fill before replace is processed | |
| 8 | ExecutionReport(B,A) | Replaced | New | 8 | 3 | 5 | |||
| 9 | ExecutionReport(B) | Trade | Filled | 8 | 8 | 0 | 5 |
Trade stream
Upon Subscription, the server will return all Trade for this client as long as the optional constraints are satisfied. Server will also send a Trade update when the order receives more fills or new fills arrive on a new order that came in as long as the optional constraints are satisfied.
Request stream of Trade messages.
TradeTrade subscription
{
  "reqid": 8,
  "type": "subscribe",
  "streams": [
    {
      "name": "Trade",
      "StartDate": "2021-09-14T00:00:00.000000Z"
    }
  ]
}
Trade response
{
  "reqid": 8,
  "type": "Trade",
  "ts": "2021-09-14T22:29:32.255949Z",
  "initial": true,
  "seqNum": 1,
  "data": [
    {
      "Timestamp": "2021-09-14T22:23:11.989845Z",
      "Symbol": "BTC-USD",
      "OrderID": "1b6b882b-e2fc-4774-ad2d-9db4df536f29",
      "TradeID": "a0ec46f2-6d0e-451a-a4f1-2a0be7d32d26",
      "Side": "Buy",
      "TransactTime": "2021-09-14T22:23:11.964531Z",
      "ExecType": "Trade",
      "Currency": "BTC",
      "Price": "47085.090668824440",
      "Quantity": "0.20000000",
      "Amount": "9417.02",
      "Fee": "0",
      "CustomerUser": "tom@company.com",
      "TradeStatus": "Confirmed",
      "AggressorSide": "Buy",
      "AmountCurrency": "USD",
      "DealtCurrency": "BTC"
    },
    {
      "Timestamp": "2021-09-14T22:26:44.515692Z",
      "Symbol": "BTC-USD",
      "OrderID": "b35b1c3b-a304-4224-919f-9db1319de188",
      "TradeID": "17f9da19-d3bd-4ba2-b29a-1f31516458f2",
      "Side": "Buy",
      "TransactTime": "2021-09-14T22:26:44.485836Z",
      "ExecType": "Trade",
      "Currency": "BTC",
      "Price": "46945.3659525",
      "Quantity": "0.10000000",
      "Amount": "4694.54",
      "Fee": "0",
      "CustomerUser": "tom@company.com",
      "TradeStatus": "Confirmed",
      "AggressorSide": "Buy",
      "AmountCurrency": "USD",
      "DealtCurrency": "BTC"
    }
  ]
}
Subscription parameters
| Key | Type | Required | Description |
|---|---|---|---|
| StartDate | string | N | If provided, the subscription will return trades that were executed after this time. An ISO-8601 UTC string of the form 2019-02-13T05:17:32.000000Z |
| EndDate | string | N | If provided, the subscription will return trades that were executed before this time. An ISO-8601 UTC string of the form 2019-02-13T05:17:32.000000Z |
| Symbol | string | N | If provided, Symbol of the security to get the orders for |
| OrderID | string | N | If provided, filter by OrderID |
| RFQID | string | N | If provided, filter by RFQID |
Response fields
| Key | Type | Required | Description |
|---|---|---|---|
| Timestamp | datetime | Y | Timestamp of the message |
| OrderID | string | Y | Server assigned Order ID, will be a UUID |
| TradeID | string | Y | Server assigned Trade ID, will be a UUID |
| Side | string | Y | "Buy" or "Sell" |
| TransactTime | datetime | Y | An ISO-8601 UTC string of the form 2019-02-13T05:17:32.000000Z |
| ExecType | string | Y | Describes the specific execution (e.g. Pending Cancel) while OrdStatus will always identify the current order status (e.g. Partially Filled). Valid values: New, Trade, Canceled, Replaced, PendingCancel, Stopped, Rejected, PendingNew, Restated, PendingReplace, CancelRejected, ReplaceRejected, PendingResume, Resumed, PendingPause, Paused, Triggered, Started |
| Currency | string | Y | Currency of Quantity |
| Price | decimal | N | Order limit price, required when OrdType=Limit |
| Quantity | decimal | Y | Trade quantity |
| Amount | decimal | Y | Trade amount |
| Fee | decimal | Y | Trade fee |
| FeeCurency | string | N | Cumulative fee currency |
| TradeStatus | string | Y | Status of the trade. Valid values: Pending, Confirmed, Canceled |
| QuoteID | string | N | Server assigned QuoteID for RFQ Orders |
| AmountCurrency | string | Y | Currency of Amount |
| RFQID | string | N | Server assigned RFQID for RFQ Orders |
| CustomerUser | string | N | The customer user associated with this trade. |
Quote stream and RFQ lifecycle
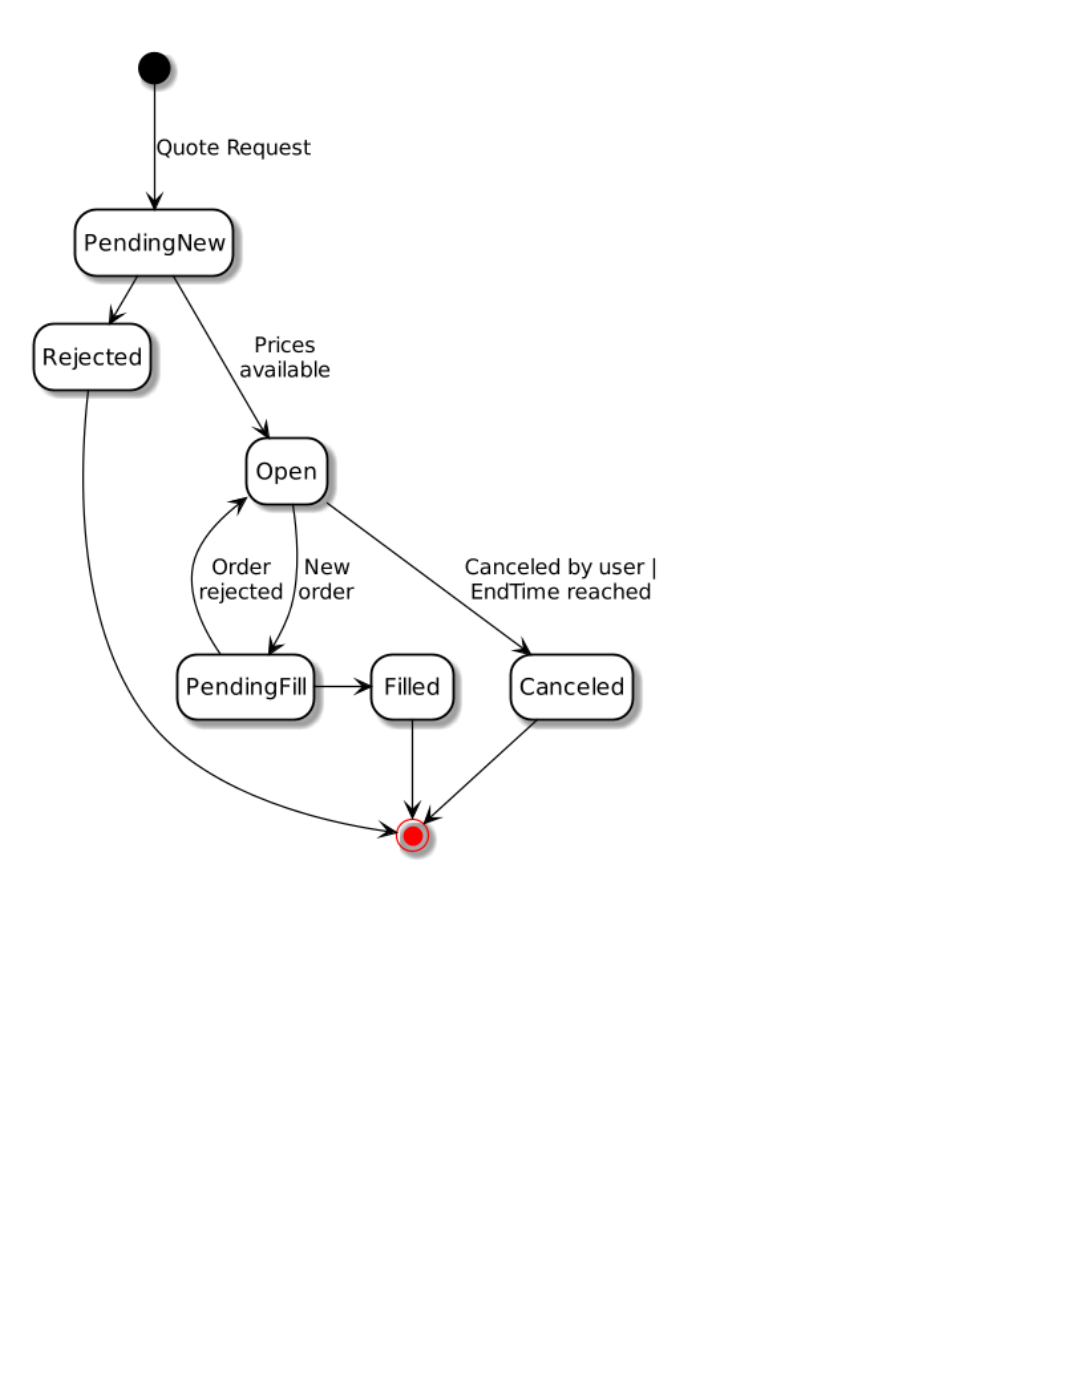
This section outlines how to request quotes from multiple dealers simultaneously and accept them using the SDM API. To send a quote request, first subscribe to the Quote stream, and the ExecutionReport stream as with orders. All quote responses are sent as Quote updates, and all order responses and updates are sent as ExecutionReport .
To request a quote, send a QuoteRequest message. The server responds with one or many Quote messages as the streaming prices update.
An in-progress Quote can be cancelled by sending a QuoteCancelRequest message. Quotes time out automatically after 3 minutes by default.
To accept a quote, send a NewOrderSingle (RFQ) message.
To generate a QuoteReqID, we recommend using a UUID4 or another globally unique identifier. QuoteReqID must be unique and with length less than or equal to 36 characters.
Request stream of Quotes.
A typical workflow to request and accept a quote would be:
- Subscribe to Quote .
- Subscribe to ExecutionReport .
- Subscribe to Trade with StartDate of the Timestamp of the last Trade processed to recover any missed trades.
- To request a quote, first generate a new QuoteReqID (see instructions below). Send a QuoteRequest specifying the QuoteReqID , OrderQty , Currency etc. for that request.
- Quote updates will be received that are able to be priced.
- To accept a quote that is received, send a NewOrderSingle referencing the RFQID and parameters depending on OrdType
- Fills will be received as ExecutionReport with ExecType=Trade .
- QuoteStatus will change to Filled when the Quote is successfully accepted.
QuoteQuote subscription
{
  "reqid": 9,
  "type": "subscribe",
  "streams": [
    {
      "name": "Quote"
    }
  ]
}
Quote response
{
  "reqid": 9,
  "type": "Quote",
  "ts": "2021-09-14T22:31:27.214025Z",
  "initial": false,
  "seqNum": 3,
  "data": [
    {
      "Timestamp": "2021-09-14T22:31:27.204209Z",
      "Symbol": "BTC-USD",
      "Currency": "BTC",
      "RFQID": "8688ceab-ea67-416c-8ce1-9b63d6c0fe4e",
      "QuoteReqID": "7feb22f0-15ab-11ec-b0a2-2554a9e1e7a4",
      "QuoteStatus": "Open",
      "QuoteID": "20e240c5-9a82-4731-809e-91b3a2bf2f49",
      "SubmitTime": "2021-09-14T22:31:27.183751Z",
      "OrderQty": "0.30000000",
      "AmountCurrency": "USD",
      "EndTime": "2021-09-14T22:31:42.183751Z",
      "BidPx": "46836.27",
      "BidAmt": "14050.88",
      "OfferPx": "46879.47",
      "OfferAmt": "14063.85",
      "ValidUntilTime": "2021-09-14T22:31:28.204209Z",
      "CustomerUser": "tom@company.com"
    }
  ]
}
Subscription parameters
| Key | Type | Required | Description |
|---|---|---|---|
| StartDate | string | N | If provided, the subscription will return quotes for rfqs that were submitted after this time. An ISO- 8601 UTC string of the form 2019-02-13T05:17:32.000000Z |
| EndDate | string | N | If provided, the subscription will return quotes for rfqs that were submitted before this time. An ISO-8601 UTC string of the form 2019-02-13T05:17:32.000000Z |
| Symbol | string | N | If provided, Symbol of the security to get the orders for |
| RFQID | string | N | If provided, filter by RFQID |
Response fields
| Key | Type | Required | Description |
|---|---|---|---|
| Timestamp | datetime | Y | Timestamp of the message |
| Symbol | string | Y | Symbol of the order security |
| Currency | string | Y | Currency of Quantity |
| RFQID | string | N | Server assigned RFQID for RFQ Orders |
| QuoteReqID | string | Y | Client assigned Quote Req ID for the quote request |
| QuoteStatus | string | Y | Status of the quote, one of PendingNew, Open, PendingCancel, Canceled, PendingFill, Filled, Rejected |
| QuoteID | string | Y | Server assigned ID for this quote update |
| QuoteRequestRejectReason | string | Y | Quote request reject reason, specified when ExecType=Rejected. Valid values: UnknownSymbol, OrderExceedsLimit, TooLateToEnter, UnknownOrder, DuplicateOrder, StaleRequest, InternalError, BrokerOption, RateLimit, ForceCancel, ImmediateOrderDidNotCross, PostOnlyOrderWouldCross, InvalidStrategy, QuoteRequestTimeout, QuoteExpired |
| SubmitTime | datetime | Y | Time of original quote request submission |
| OrderQty | decimal | Y | Order quantity |
| AmountCurrency | string | Y | Currency of Amount |
| EndTime | datetime | Y | End time of RFQ; an ISO-8601 UTC string of the form 2019-02-13T05:17:32.000000Z |
| Side | string | Y | "Buy" or "Sell" |
| TradedPx | decimal | N | The price of the trade if the quote is filled. This will be an all-in price that includes fees |
| TradedQty | decimal | N | The quantity of the trade if the quote is filled in units of Currency |
| TradedAmt | decimal | N | The amount of the trade if the quote is filled in units of AmountCurrency |
| TradedSide | string | N | The side of the trade if the quote is filled |
| BidPx | decimal | N | Bid quote price |
| BidAmt | decimal | N | Bid quote amount in units of AmountCurrency |
| OfferPx | decimal | N | Offer quote price |
| OfferAmt | decimal | N | Offer quote amount in units of AmountCurrency |
| ValidUntilTime | datetime | Y | The expire time of the quote. An ISO-8601 UTC string of the form 2019-02- 13T05:17:32.000000Z |
| Text | string | N | Human readable error message |
| CustomerUser | string | N | The customer user associated with this quote. |
QuoteRequest and QuoteCancelRequest commands
Command used to request a quote thereby opening a new RFQ. Results of this command will be visible in the Quote stream.
Command used to cancel an open RFQ. Results of this command will be visible in the Quote stream.
QuoteRequestSubmit QuoteRequest
{
  "reqid": 15,
  "type": "QuoteRequest",
  "data": [
    {
      "QuoteReqID": "8e9540d0-15db-11ec-b5e7-7f4881f01b7d",
      "OrderQty": "0.75",
      "Currency": "BTC",
      "Symbol": "BTC-USD",
      "TransactTime": "2021-09-15T04:15:27.581000Z",
      "Parameters": {}
    }
  ]
}
QuoteRequest command data
| Key | Type | Required | Description |
|---|---|---|---|
| Timestamp | datetime | N | Timestamp of the message |
| Symbol | string | Y | Symbol of the security to submit an order on |
| Currency | string | Y | The currency that the quantity is specified in. |
| QuoteReqID | string | Y | Unique ID for this request, usually a UUID |
| Side | string | N | Optional side for a one sided request, either "Buy" or "Sell". Leave blank for a two way quote |
| OrderQty | decimal | Y | Requested quantity in units of Currency |
| TransactTime | datetime | N | An ISO-8601 UTC string of the form 2019-02-13T05:17:32.000000Z |
QuoteCancelRequestSubmit QuoteCancelRequest
{
  "reqid": 16,
  "type": "QuoteCancelRequest",
  "data": [
    {
      "QuoteReqID": "8e9540d0-15db-11ec-b5e7-7f4881f01b7d",
      "RFQID": "f47bfb99-4d1e-4179-b62c-a96e83cc93ba",
      "TransactTime": "2021-09-15T04:15:24.581000Z"
    }
  ]
}
QuoteCancelRequest command data
| Key | Type | Required | Description |
|---|---|---|---|
| QuoteReqID | string | Y | QuoteReqID from the request to cancel |
| RFQID | string | Y | RFQID to cancel, required and must align with QuoteReqID |
| TransactTime | datetime | Y | An ISO-8601 UTC string of the form 2019-02-13T05:17:32.000000Z |
Balance stream
Request for stream of Balance updates
BalanceBalance subscription
{
  "reqid": 11,
  "type": "subscribe",
  "streams": [
    {
      "name": "Balance",
      "EquivalentCurrency": "USD"
    }
  ]
}
Balance response
{
  "reqid": 11,
  "type": "Balance",
  "ts": "2021-09-16T16:17:06.892914Z",
  "initial": true,
  "seqNum": 1,
  "data": [
    {
      "Currency": "USD",
      "Amount": "-1928479.77953598",
      "AvailableAmount": "-1928479.77953598",
      "Equivalent": {
        "Currency": "USD",
        "Amount": "-1928479.78",
        "AvailableAmount": "-1928479.78"
      }
    },
    {
      "Currency": "BTC",
      "Amount": "40.15480673",
      "AvailableAmount": "40.15480673",
      "Equivalent": {
        "Currency": "USD",
        "Amount": "1930241.56",
        "AvailableAmount": "1930241.56"
      }
    },
    {
      "Currency": "ETH",
      "Amount": "11.00000000",
      "AvailableAmount": "11.00000000",
      "Equivalent": {
        "Currency": "USD",
        "Amount": "39753.78",
        "AvailableAmount": "39753.78"
      }
    },
    {
      "Currency": "BCH",
      "Amount": "23.68787010",
      "AvailableAmount": "23.68787010",
      "Equivalent": {
        "Currency": "USD",
        "Amount": "15066.67",
        "AvailableAmount": "15066.67"
      }
    },
    {
      "Currency": "ADA",
      "Amount": "10330.26832917",
      "AvailableAmount": "10330.26832917",
      "Equivalent": {
        "Currency": "USD",
        "Amount": "25340.27",
        "AvailableAmount": "25340.27"
      }
    }
  ]
}
Subscription parameters
| Key | Type | Required | Description |
|---|---|---|---|
| Currencies | string[] | N | Optional list of currencies to filter these balance updates by, default is all available currencies |
| EquivalentCurrency | string | N | If provided, will provide converted equivalent amounts of each currency in the provided Equivalent Currency |
Response fields
| Key | Type | Required | Description |
|---|---|---|---|
| Currency | string | Y | Currency of this balance update |
| Amount | decimal | Y | Current balance amount in the specified currency |
| AvailableAmount | decimal | Y | Amount available for trading right now |
| Equivalent | object[] | N | If requested equivalent balance amount, will provide a Balance update in the specified equivalent currency |
| → Currency | string | N | Requested Equivalent Currency |
| → Amount | decimal | N | Amount of this balance in the equivalent currency |
| → AvailableAmount | decimal | N | Equivalent amount of amount available for trading right now |
Exposure stream
Request for stream of Exposure updates
ExposureExposure subscription
{
  "reqid": 11,
  "type": "subscribe",
  "streams": [
    {
      "name": "Exposure"
    }
  ]
}
Exposure response
{
  "reqid": 11,
  "type": "Exposure",
  "ts": "2021-09-16T16:17:06.892914Z",
  "initial": true,
  "seqNum": 1,
  "data": [
    {
      "ExposureCurrency": "USD",
      "Exposure": "1000000",
      "ExposureLimit": "5000000",
      "Status": "Online",
      "Timestamp": "2021-09-16T16:17:06.892914Z"
    }
  ]
}
Response fields
| Key | Type | Required | Description |
|---|---|---|---|
| ExposureCurrency | string | Y | The currency all exposure values are expressed in |
| Exposure | decimal | Y | Current credit utilization expressed in the ExposureCurrency |
| ExposureLimit | decimal | Y | Credit limit expressed in the ExposureCurrency |
| Status | status | Y | Status of the exposure information. Possible values: Online, Offline |
| Timestamp | status | Y | The last time the credit was updated as an ISO-8601 UTC string of the form 2019-02- 13T05:17:32.000000Z. |
BalanceTransaction stream
Request stream of Balance Transaction Updates
Subscription Parameters: None
BalanceTransactionBalance transaction subscription
{
  "reqid": 9,
  "type": "subscribe",
  "streams": [
    {
      "name": "BalanceTransaction"
    }
  ]
}
Balance transaction response
{
  "reqid": 9,
  "type": "BalanceTransaction",
  "ts": "2023-02-10T16:49:18.300588Z",
  "initial": true,
  "seqNum": 1,
  "data": [
    {
      "Timestamp": "2023-02-10T16:50:12.562757Z",
      "ClReqID": "06b78113c1454174b9e403a1245d67ea",
      "TransactionID": "1D2FBR4J00R00",
      "Revision": 0,
      "TransactionType": "Withdrawal",
      "MarketAccount": "default",
      "Quantity": "1",
      "Currency": "ETH",
      "Status": "PendingApproval",
      "LastUpdateTime": "2023-02-10T16:50:12.556229Z"
    }
  ]
}
Response fields
| Key | Type | Required | Description |
|---|---|---|---|
| Timestamp | datetime | Y | Timestamp of the message |
| Currency | string | Y | Currency of Quantity |
| ClReqID | string | Y | Client assigned Request ID |
| Status | string | Y | Status of the quote, one of PendingApproval, PendingTransfer, Rejected, Completed |
| TransactionID | string | Y | Server assigned ID for this transaction |
| LastUpdateTime | datetime | Y | Time of most recent update to the Transaction |
| Quantity | decimal | Y | Trnasaction quantity |
| MarketAccount | string | Y | Account to apply this transaction to |
| Revision | string | Y | Revision of this transaction |
NewWithdrawRequest command
Command used to request a new withdrawal
NewWithdrawRequestSubmit NewWithdrawRequest
{
  "reqid": 34,
  "type": "NewWithdrawRequest",
  "data": [
    {
      "Quantity": "1",
      "Currency": "ETH",
      "MarketAccount": "default",
      "RoutingInfo": {
        "WalletAddress": "XXYYZZ",
        "Memo": "",
        "DestinationTag": ""
      },
      "ClReqID": "06b78113c1454174b9e403a1245d67ea"
    }
  ]
}
Command data
| Key | Type | Required | Description |
|---|---|---|---|
| Currency | string | Y | The currency that the quantity is specified in. |
| ClReqID | string | Y | Unique ID for this request, usually a UUID |
| Quantity | decimal | Y | Requested quantity in units of Currency |
| TransactTime | datetime | N | An ISO-8601 UTC string of the form 2019-02-13T05:17:32.000000Z |
| RoutingInfo | object | N | Provides routing info for the transaction such as WalletAddress |
User stream
Request for updates for this customer user. No subscription parameters.
UserUser subscription
{
  "reqid": 10,
  "type": "subscribe",
  "streams": [
    {
      "name": "User"
    }
  ]
}
User response
{
  "reqid": 10,
  "type": "User",
  "ts": "2021-09-15T03:33:07.545223Z",
  "initial": true,
  "seqNum": 1,
  "data": [
    {
      "CustomerUserID": "174K1Q9GC0C00",
      "Email": "tom@company.com",
      "DisplayName": "Tom",
      "Config": [
        {
          "Timestamp": 1628004805337309202,
          "CustomerUserID": "174K1Q9GC0C00",
          "Key": "recentSymbols",
          "Value": "{\"BTC-USD\":[1626111502357],\"ADA-USD\":[1626732116743],\"BCH-USD\":[1628004751665]}"
        },
        {
          "Timestamp": 1628004805377207692,
          "CustomerUserID": "174K1Q9GC0C00",
          "Key": "symbol",
          "Value": "\"BTC-USD\""
        }
      ]
    }
  ]
}
Response fields
| Key | Type | Required | Description |
|---|---|---|---|
| CustomerUserID | string | Y | Server assigned ID of this Customer User |
| string | Y | Email of Customer User | |
| DisplayName | string | Y | Friendly name for customer user |
| Config | object[] | Y | List of user config settings |
| → Timestamp | datetime | Y | Timestamp of config setting update |
| → CustomerUserID | string | Y | Customer User for this config setting |
| → Mode | string | Y | Setting whether config is enabled, values Enabled or Disabled |
| → Key | string | Y | User config key |
| → Value | string | Y | User config value |
UserConfig command
Command used to update user config on behalf of session user. Results of this command will be visible in the User stream.
UserConfigSubmit UserConfig
{
  "reqid": 18,
  "type": "UserConfig",
  "data": [
    {
      "Key": "symbol",
      "Value": "\"ETH-BTC\""
    }
  ]
}
Command data
| Key | Type | Required | Description |
|---|---|---|---|
| Timestamp | datetime | N | Timestamp of the message |
| Mode | string | N | Optional mode on config, either Enabled or Disabled |
| Key | string | Y | Key of config |
| Value | string | N | Value of config |
OHLCV endpoint
The OHLCV API provides data on the specified symbols.
Get the open, high, low, close, and volume parameters for a given symbol and resolution
/v1/symbols/<symbol>/ohlcv/<resolution>Example request
GET /v1/symbols/BTC-USD/ohlcv/1hQuery parameters
| Name | Type | Description |
|---|---|---|
| startDate | string | If provided, will return data starting at this time. An ISO-8601 UTC string of the form 2019-02-13T05:17:32.000000Z. |
| endDate | string | If provided, will return data ending at this time. An ISO-8601 UTC string of the form 2019-02-13T05:17:32.000000Z. |
OHLCV response
{
  "type": "OHLCV",
  "ts": "2019-09-16T14:57:19.785823Z",
  "data": [{
      "Timestamp":"2023-02-27T10:52:00.000000Z",
      "Symbol":"BTC-USD",
      "Open":"23413.30000",
      "High":"23418.24",
      "Low":"23399.46",
      "Close":"23407.10000",
      "Volume":"0.49309984",
      "Ticks":74
        }
      ]
    }
  ]
}
Response fields
| Key | Type | Description |
|---|---|---|
| Timestamp | datetime | The start time for this interval |
| Symbol | string | A unique symbol for this security. |
| Volume | decimal | Total base-currency volume traded (if any) for the symbol in the time interval. |
| Open | decimal | First trade price (if any) for the symbol in the time interval. |
| Close | decimal | Last trade price (if any) for the symbol in the time interval. |
| High | decimal | Highest traded price (if any) for the symbol in the time interval. |
| Low | decimal | Lowest traded price (if any) for the symbol in the time interval. |
| Ticks | decimal | Total number of ticks for the symbol in the time interval |
FIX connectivity, configuration, and protocol
The FIX API provides the user with access to real-time market data subscription and orders execution. Additional data is available via the websocket API.
Connectivity is made to the Secure Digital API via the internet. The following will be provided to the client during onboarding: ● Hostname ● Port number
Secure Digital acts as an acceptor for all FIX sessions. FIX session information will be provided during onboarding: ● SenderCompID ● TargetCompID ● StartTime ● EndTime
Sessions can be configured with or without FIX session level message recovery. A typical setup includes 2 sessions: ● A FIX session for market data with recovery disabled. ● A FIX session for orders submission with recovery enabled.
Last updated: Feb 27, 2025
See the FIX.4.4 spec available at https://www.fixtrading.org/standards/fix-4-4/.
Onboarding values
| Connectivity | Session configuration |
|---|---|
| Hostname | SenderCompID |
| Port number | TargetCompID |
| StartTime | |
| EndTime |
After FIX Logon, the client should send a MarketDataRequest to subscribe to market data snapshots. On subscription, the client can choose to subscribe to aggregated prices as price or size levels. After subscription, Secure Digital will stream market data full snapshot updates as the market prices change. Market data delta updates will be supported in a future release.
The orders API supports order submission. All orders can be amended and canceled via the API. Specifying order strategy and algo parameters will be supported in a future release.
By default, all open orders submitted via the FIX session will be canceled on disconnect. Cancel on Disconnect does not affect other orders for the same user that were submitted on other sessions, or orders that were explicitly placed as CancelOnDisconnect=N, see New Order Single.
Sessions will receive a full drop copy for all execution reports associated with the session user. This includes orders submitted via the UI or other protocols (websocket, etc).
The API sends UTC timestamps with millisecond precision. For example: 20140515-19:49:56.659. The API accepts UTC timestamps with second, millisecond, or microsecond precision in the format YYYYddmm-HH:MM:SS.ffffff. For example, 20140515-19:49:56, 20140515-19:49:56.659, or 20140515-19:49:56.659441.
FIX standard header and trailer
Standard Header
| Tag | Field Name | Req'd | Comments |
|---|---|---|---|
| 8 | BeginString | Y | FIX.4.4. Must be the first field in the message |
| 9 | BodyLength | Y | Must be the second field in the message |
| 35 | MsgType | Y | Must be the third field in the message |
| 49 | SenderCompID | Y | Provided by Secure Digital during onboarding |
| 56 | TargetCompID | Y | Provided by Secure Digital during onboarding |
| 34 | MsgSeqNum | Y | |
| 43 | PossDupFlag | N | Always required for retransmitted messages, whether prompted by the sending system or as the result of a resend request. |
| 97 | PossResend | N | Required when the message may be duplicate of another message sent under a different sequence number. |
| 52 | SendingTime | Y | |
| 122 | OrigSendingTime | N | Required for message re-sent as a result of a ResendRequest. If data is not available set to same value as SendingTime <52> |
Standard Header
| Tag | Field Name | Req'd | Comments |
|---|---|---|---|
| 10 | CheckSum | Y | Three byte, simple checksum. See the FIX spec for details |
FIX Logon and signature
The signature is created by concatenating
- SendingTime (52) as a string
- ASCII 01 value
- SeqNum (34) as a string
- ASCII 01 value
- SenderCompID (49)
- ASCII 01 value
- TargetCompID (56)
Logon fields
| Tag | Field Name | Req'd | Comments |
|---|---|---|---|
| <MessageHeader> | Y | MsgType <35> = A | |
| 108 | HeartBtInt | Y | Note same value used by both sides |
| 141 | ResetSeqNumFlag | N | Indicates both sides of a FIX session should reset sequence numbers |
| 96 | RawData | Y | Contains signature (see below for creating a signature) |
| 554 | Password | Y | Contains the API Key for the Customer user |
| <MessageTrailer> | Y |
This string is then signed using the HMAC SHA-256 Algorithm and the API Secret for the API Key. Sample Java code showing how this can be done programmatically. Note this sample relies on Apache Commons-Codec and QuickFIX for Java.
Java signing example
/**
 * Takes a Message, an apiKey and apiSecret and uses the HMAC-SHA256 algorithm to sign a FIX message by appending
 * the sending-time sequenceNumber, SenderCompID and TargetCompID with \u0001 separator and signing using the
 * secret, putting it into the RawBytes in Base64 encoding.
 */
private static void signLogon(
    final Message message,
    final SessionID sessionId,
    final String apiKey,
    final String apiSecret
) throws FieldNotFound {
    final var senderCompId = sessionId.getSenderCompID();
    final var targetCompId = sessionId.getTargetCompID();
    final var sendingTime = message.getString(SendingTime.FIELD);
    final var seqNum = message.getInt(MsgSeqNum.FIELD);
    final var sep = "\u0001";
    final var hmac = sign(
        apiSecret,
        sendingTime + sep + seqNum + sep + senderCompId + sep + targetCompId
    );

    message.setString(Password.FIELD, apiKey);
    message.setInt(RawDataLength.FIELD, hmac.length());
    message.setString(RawData.FIELD, hmac);
}

private static String sign(final String apiSecret, final String data) {
    final var mac = HmacUtils.getInitializedMac(
        HmacAlgorithms.HMAC_SHA_256,
        apiSecret.getBytes()
    );
    final var encodedBytes = mac.doFinal(data.getBytes());
    final var encoder = Base64.getUrlEncoder(); //URL Safe Base64
    return encoder.encodeToString(encodedBytes);
}
FIX session-level messages
Heartbeat (35=0)
| Tag | Field Name | Req'd | Comments |
|---|---|---|---|
| <MessageHeader> | Y | MsgType <35> = 0 | |
| 112 | TestReqID | Y | Required when the heartbeat is the result of a Test Request message |
| <MessageTrailer> | Y |
Test Request (35=1)
| Tag | Field Name | Req'd | Comments |
|---|---|---|---|
| <MessageHeader> | Y | MsgType <35> = 1 | |
| 112 | TestReqID | Y | |
| <MessageTrailer> | Y |
Resend Request (35=2)
| Tag | Field Name | Req'd | Comments |
|---|---|---|---|
| <MessageHeader> | Y | MsgType <35> = 2 | |
| 7 | BeginSeqNo | Y | |
| 16 | EndSeqNo | Y | |
| <MessageTrailer> | Y |
Reject (35=3)
| Tag | Field Name | Req'd | Comments |
|---|---|---|---|
| <MessageHeader> | Y | MsgType <35> = 3 | |
| 45 | RefSeqNum | Y | MsgSeqNum of rejected message |
| 371 | RefTagID | N | The tag number of the FIX field being referenced |
| 372 | RefMsgType | N | The MsgType of the FIX message being referenced |
| 373 | SessionRejectReason | N | Code to identify reason for a session-level Reject message |
| 58 | Text | N | Where possible, message to explain reason for rejection |
| <MessageTrailer> | Y |
Sequence Reset (35=4)
| Tag | Field Name | Req'd | Comments |
|---|---|---|---|
| <MessageHeader> | Y | MsgType <35> = 4 | |
| 123 | GapFillFlag | N | |
| 36 | NewSeqNo | Y | |
| <MessageTrailer> | Y |
Logout (35=5)
| Tag | Field Name | Req'd | Comments |
|---|---|---|---|
| <MessageHeader> | Y | MsgType <35> = 5 | |
| 58 | Text | N | |
| <MessageTrailer> | Y |
FIX market data messages
Market Data Request (35=V)
| Tag | Field Name | Req'd | Comments |
|---|---|---|---|
| <MessageHeader> | Y | MsgType <35> = V | |
| 262 | MDReqID | Y | Must be unique, or the ID of previous Market Data Request to disable if SubscriptionRequestType(263) = 2 (Disable previous Snapshot + Updates Request). |
| 263 | SubscriptionRequestType | Y | 0 = Snapshot, 1 = Snapshot + Updates (Subscribe) 2 = Unsubscribe |
| 264 | MarketDepth | N | Depth of market for Book Snapshot / Incremental updates 0 - full book depth 1 - top of book 2 and above - book depth (number of levels) Exactly one of tag 264 or tag 20020 must be specified. |
| 1070 | MDQuoteType | N | Type of liquidity to be included 0 - Indicative 1 - Tradeable (i.e., Firm) |
| 20020 | NoSizeBucketsSegments | N | A list of sizes to return price levels for. Used to ask for prices of aggregated sizes. Exactly one of tag 264 or tag 20020 must be specified. Note: only supported with MDUpdateType(265) = 0 (Full refresh) |
| →20021 | SizeBucket | Y | Identifies a single size bucket |
| →55 | Symbol | Y | The symbol of the currency pair to subscribe to. For example, BTC-USD |
| <MessageTrailer> | Y |
Note : that exactly one of either Depth, or SizeBucket must be specified. For example, specifying both Depth and SizeBuckets will result in an error.
Market Data Request Reject (35=Y)
| Tag | Field Name | Req'd | Comments |
|---|---|---|---|
| <MessageHeader> | Y | MsgType <35> = Y | |
| 262 | MDReqID | Y | Refers to the MDReqID of the request |
| 58 | Text | N | |
| <MessageTrailer> | Y |
Market Data Snapshot Full Refresh (35=W)
| Tag | Field Name | Req'd | Comments |
|---|---|---|---|
| <MessageHeader> | Y | MsgType <35> = W | |
| 262 | MDReqID | Y | Refers to the MDReqID of the request. |
| 55 | Symbol | Y | Symbol updated by the Market Data Entry. |
| 268 | NoMDEntries | Y | Number of entries following. |
| →269 | MDEntryType | Y | Type of market data entry. 0 = Bid 1 = Offer Required if NoMDEntries(268) > 0. |
| →270 | MDEntryPx | Y | Price of the Market Data Entry. |
| →271 | MDEntrySize | Y | Quantity represented by the Market Data Entry. |
| →272 | MDEntryDate | Y | Date of Market Data Entry. |
| →273 | MDEntryTime | Y | Time of Market Data Entry. |
| <MessageTrailer> | Y |
FIX order messages
The NewOrderSingle message is used to submit a new order. Market and Limit orders are currently supported. Orders are routed using the default routing strategy. Specifying order strategy and algo parameters will be supported in a future release.
The OrderCancelRequest message is used to cancel an existing order.
The OrderCancelReplaceRequest message is used to amend the price, quantity, or markets for an existing order.
The ExecutionReport message is used to acknowledge/reject an order or changes to an order, and to relay order status and fill updates.
The OrderCancelReject message is used to reject invalid cancel or cancel/replace requests.
The NewOrderSingle message is used to submit a new order. Market and Limit orders are currently supported. Orders are routed using the default routing strategy. Specifying order strategy and algo parameters will be supported in a future release.
New Order Single (35=D)
| Tag | Field Name | Req'd | Comments |
|---|---|---|---|
| <MessageHeader> | Y | MsgType <35> = D | |
| 1 | Account | N | The specific account for this order. Required if multiple accounts are enabled |
| 11 | ClOrdID | Y | Unique identifier for Order as assigned by the client. Must be <= 36 characters. UUIDs are recommended. |
| 55 | Symbol | Y | The symbol of the currency pair to place an order on. For example, BTC-USD |
| 54 | Side | Y | Side of order 1 = Buy 2 = Sell |
| 40 | OrdType | Y | Order type 1 = Market 2 = Limit A = LimitAllIn, requested price/size includes fees |
| 38 | OrderQty | Y | Size of the order |
| 15 | Currency | N | The currency the quantity is specified in. If not specified, defaults to the base currency for the symbol. |
| 44 | Price | N | Price of the order. Required for limit orders. |
| 59 | TimeInForce | Y | Specifies how long the order remains in effect. 1 = Good Till Cancel (GTC) 3 = Immediate Or Cancel (IOC) 4 = Fill Or Kill (FOK) |
| 60 | TransactTime | Y | Business timestamp for this request. |
| 126 | ExpireTime | N | Optional expiration time for the order. Only valid on orders with TimeInForce=1 (GTC). UTC Timestamp. |
| 168 | EffectiveTime | N | Time at which this order will activate and begin sending orders to the market. UTC Timestamp. |
| 847 | TargetStrategy | N | Allows Specifying an Order Strategy Type See Order Strategies |
| 957 | NoStrategyParams | N | The number of strategy parameter repeating groups |
| 958 | StrategyParameterName | N | The name of the StrategyParameter being set |
| 960 | StrategyParameterValue | N | The value for the StrategyParameter being set |
| 20030 | CancelOnDisconnect | N | Whether or not this order should be canceled when this session is disconnected, Y / N. Defaults to Y. |
| <MessageTrailer> | Y |
Order Cancel Request (35=F)
| Tag | Field Name | Req'd | Comments |
|---|---|---|---|
| <MessageHeader> | Y | MsgType <35> = F | |
| 11 | ClOrdID | Y | Unique ID of cancel request as assigned by the client. Must be <= 36 characters. UUIDs are recommended. |
| 41 | OrigClOrdID | Y | ClOrdID(11) of the previous non-rejected order. |
| 55 | Symbol | Y | The symbol of the currency pair of the order. For example, BTC-USD |
| 54 | Side | Y | Side of order 1 = Buy 2 = Sell |
| 60 | TransactTime | Y | Business timestamp for this request. |
| <MessageTrailer> | Y |
Order Cancel Replace Request (35=G)
| Tag | Field Name | Req'd | Comments |
|---|---|---|---|
| <MessageHeader> | Y | MsgType <35> = G | |
| 11 | ClOrdID | Y | Unique ID of cancel request as assigned by the client. Must be <= 36 characters. UUIDs are recommended. |
| 41 | OrigClOrdID | Y | ClOrdID(11) of the previous non-rejected order. |
| 55 | Symbol | Y | The symbol of the currency pair of the order. For example, BTC-USD |
| 54 | Side | Y | Side of order 1 = Buy 2 = Sell |
| 40 | OrdType | Y | Order type 1 = Market 2 = Limit A = LimitAllIn, requested price/size includes fees |
| 38 | OrderQty | Y | Size of the order |
| 44 | Price | N | Price of the order. Required for limit orders. |
| 60 | TransactTime | Y | Business timestamp for this request. |
| <MessageTrailer> | Y |
Execution Report (35=8)
| Tag | Field Name | Req'd | Comments |
|---|---|---|---|
| <MessageHeader> | Y | MsgType <35> = 8 | |
| 11 | ClOrdID | N | ClOrdID of the order. |
| 41 | OrigClOrdID | N | Set to the ClOrdID of the previous accepted order when responding to a Cancel or Cancel/Replace request |
| 37 | OrderID | Y | Unique identifier of most recent order as assigned by Secure Digital. |
| 55 | Symbol | Y | The symbol of the currency pair of the order. For example, BTC-USD |
| 54 | Side | Y | Side of order 1 = Buy 2 = Sell |
| 38 | OrderQty | Y | Size of the order |
| 44 | Price | N | Price of the order. Required for limit orders. |
| 60 | TransactTime | N | Business timestamp for this execution. |
| 17 | ExecID | Y | Unique identifier of execution message as assigned by Secure Digital. |
| 527 | SecondaryExecID | N | Unique identifier of execution message as assigned by the exchange or liquidity provider. Only specified when ExecType=Trade. |
| 150 | ExecType | Y | Describes the specific ExecutionRpt (e.g. Pending Cancel) while OrdStatus(39) will always identify the current order status (e.g. Partially Filled). 0 = New 3 = Done for day 4 = Canceled 5 = Replaced 6 = Pending Cancel (e.g. result of Order Cancel Request) 8 = Rejected A = Pending New E = Pending Replace (e.g. result of Order Cancel/Replace Request) F = Trade (partial fill or fill) |
| 59 | TimeInForce | Y | Specifies how long the order remains in effect. 1 = Good Till Cancel (GTC) 3 = Immediate Or Cancel (IOC) 4 = Fill Or Kill (FOK) |
| 40 | OrdType | Y | Order type 1 = Market 2 = Limit |
| 39 | OrdStatus | Y | Describes the current state of the order, same scope as OrderQty, CumQty, LeavesQty, and AvgPx 0 = New 1 = Partially filled 2 = Filled 3 = Done for day 4 = Canceled 6 = Pending Cancel (i.e. result of Order Cancel Request) 8 = Rejected A = Pending New E = Pending Replace (i.e. result of Order Cancel/Replace Request) |
| 151 | LeavesQty | Y | Quantity open for further execution. If the OrdStatus(39) is = 4 (Canceled), 3 (Done For Day), or 8 (Rejected) (in which case the order is no longer active) then LeavesQty(151) could be 0, otherwise LeavesQty(151) = OrderQty(38) - CumQty(14). |
| 14 | CumQty | Y | Currently executed quantity for chain of orders. |
| 6 | AvgPx | Y | Calculated average price of all fills on this order. |
| 103 | OrdRejReason | N | For optional use with ExecType = 8 (Rejected) 0 = Broker / Exchange option 1 = Unknown symbol 2 = Exchange closed 3 = Order exceeds limit 5 = Unknown order 6 = Duplicate Order (e.g. dupe ClOrdID) 7 = Duplicate of a verbally communicated order 8 = Stale order |
| 31 | LastPx | N | Price of this (last) fill. Required if ExecType(150) = ExecType = F (Trade) |
| 32 | LastQty | N | Quantity bought/sold on this (last) fill. Required if ExecType(150) = F (Trade) |
| 381 | GrossTradeAmt | N | Last amount traded (i.e. quantity * price) expressed in units of counter currency. Required if ExecType(150) = F (Trade) |
| 4015 | CumAmt | N | Total amount traded (i.e. quantity * price) expressed in units of counter currency. |
| 4016 | CumFee | N | Total fee expressed in units of FeeCurrency. |
| 4033 | LastFee | N | Last fee expressed in units of FeeCurrency |
| 4034 | LastFeeCurrency | N | Currency of the Fee |
| 20030 | CancelOnDisconnect | N | Whether or not this order will be canceled when this session is disconnected, Y / N |
| 20032 | DecisionStatus | N | The current decision-status of the order. A = Active (default) P = Paused U = Pending Pause R = Pending Resume W = Waiting for StartTime T = Waiting for Trigger Paused / Staged orders can be edited and resumed from the Secure Digital UI. Pending statuses are intermediate states. |
| 58 | Text | N | |
| <MessageTrailer> | Y |
Order Cancel Reject (35=9)
| Tag | Field Name | Req'd | Comments |
|---|---|---|---|
| <MessageHeader> | Y | MsgType <35> = 9 | |
| 11 | ClOrdID | Y | ClOrdID(11) which could not be canceled/replaced. |
| 41 | OrigClOrdID | Y | ClOrdID of the previous accepted order |
| 37 | OrderID | Y | Unique identifier of most recent order as assigned by Secure Digital. If CxlRejReason="Unknown order", then will be "NONE". |
| 60 | TransactTime | N | Business timestamp for this reject. |
| 39 | OrdStatus | Y | Identifies current status of order. 0 = New 1 = Partially filled 2 = Filled 4 = Canceled 6 = Pending Cancel (i.e. result of Order Cancel Request) 8 = Rejected A = Pending New E = Pending Replace (i.e. result of Order Cancel/Replace Request) |
| 434 | CxlRejResponseTo | Y | Identifies the type of request that a Cancel Reject is in response to. 1 = Order cancel request 2 = Order cancel/replace request |
| 102 | CxlRejReason | N | Code to identify reason for cancel rejection. 0 = Too late to cancel 1 = Unknown order 2 = Broker / Exchange Option 3 = Order already in Pending Cancel or Pending Replace status |
| 58 | Text | N | |
| <MessageTrailer> | Y |
FIX Security List messages
The Security List message is used to return a list of securities that matches the criteria specified in the Security List Request.
Security List Request (35=x)
| Tag | Field Name | Req'd | Comments |
|---|---|---|---|
| <MessageHeader> | Y | MsgType <35> = x | |
| 320 | SecurityReqID | Y | Unique ID to identify this request |
| 559 | SecurityListRequestType | Y | Identifies the type of Security List Request 4 = ALL_SECURITIES |
| <MessageTrailer> | Y |
Security List (35=y)
| Tag | Field Name | Req'd | Comments |
|---|---|---|---|
| <MessageHeader> | Y | MsgType <35> = y | |
| 320 | SecurityReqID | Y | Unique ID to identify this request |
| 322 | SecurityResponseID | Y | Identifier for the SecurityList message |
| 560 | SecurityRequestResult | Y | Result of the Security Request Identified by the SecurityReqID 0 = Valid Request 1 = invalid or Unsupported Request 2 = No instruments found that match the selection criteria 3 = Not authorized to retrieve instrument data 4 = Instrument data temporarily unavailable 5 = Request for instrument data not supported |
| 393 | TotalNoRelatedSym | N | Used to indicate the total number of securities being returned for this request. Used in the event that message fragmentation is required |
| 893 | LastFragment | N | Indicates whether this is the last fragment in a sequence of message fragments. Only required where message has been fragmented |
| 146 | NoRelatedSym | ||
| Component Block <Instrument> | Y if 560=0 | ||
| →55 | Symbol | Y | Common “human understood” representation of the security |
| →48 | SecurityID | Y | Internal Secure Digital ID for Security - for information only |
| →561 | RoundLot | Y | The trading lot size of a security |
| →562 | MinTradeVol | Y | Minimum Trading Volume for a security |
| →969 | MinPriceIncrement | Y | The smallest difference between quoted prices for this instrument |
| →1140 | MaxTradeVol | Y | Maximum Size for an order on this security |
| <MessageTrailer> | Y |
FIX order strategies
Order routing strategies are specified for New Order Single Messages (35=D) using the TargetStrategy(847) tag and the NoStrategyParameters(950) repeating group to specify the required parameters for the strategy.
StopLimit parameters
| Parameter Name | Type | Required | Description |
|---|---|---|---|
| TriggerPrice | Price | Y | The price that must be met to trigger execution of the order with the configured limit price. |
| TriggerSource | String | N | Optional aggregation which will be used to construct the order's trigger reference rate. |
| EndTime | String | N | Optional expiration time for the order. An ISO-8601 UTC string of the form 2019-02-13T05:17:32.000000Z |
This strategy will only place the order once the specified stop price has been met. For a Buy StopLimit order, the stop price must be _above_ the current market price. For a Sell StopLimit order, the stop price must be _below_ the current market price. To place a StopLimit order, you must send in TargetStrategy(847)=StopLimit
TakeProfitLimit parameters
| Parameter Name | Type | Required | Description |
|---|---|---|---|
| TriggerPrice | Price | Y | The price that must be met to trigger execution of the order with the configured limit price. |
| TriggerSource | String | N | Optional aggregation which will be used to construct the order's trigger reference rate. |
| EndTime | String | N | Optional expiration time for the order. An ISO-8601 UTC string of the form 2019-02-13T05:17:32.000000Z |
This strategy will only place the order once the specified take profit price has been met. For a Buy TakeProfitLimit order, the take profit price must be _below_ the current market price. For a Sell TakeProfitLimit order, the take profit price must be _above_ the current market price. To place a TakeProfitLimit order, you must send in TargetStrategy(847)=TakeProfitLimit
FIX order state change matrices
Filled order
| Time | Request (ClOrdID,OrigClOrdID) | Response (ClOrdID,OrigClOrdID) | ExecType | OrdStatus | OrderQty | CumQty | LeavesQty | LastQty | Comment |
|---|---|---|---|---|---|---|---|---|---|
| 1 | NewOrderSingle(A) | 10 | |||||||
| 2 | ExecutionReport(A) | PendingNew | PendingNew | 10 | 0 | 10 | |||
| 3 | ExecutionReport(A) | Rejected | Rejected | 10 | 0 | 10 | If order is rejected | ||
| 3 | ExecutionReport(A) | New | New | 10 | 0 | 10 | |||
| 4 | ExecutionReport(A) | Trade | PartiallyFilled | 10 | 2 | 8 | 2 | ||
| 5 | ExecutionReport(A) | Trade | PartiallyFilled | 10 | 3 | 7 | 1 | ||
| 6 | ExecutionReport(A) | Trade | Filled | 10 | 10 | 0 | 7 |
Canceled order
| Time | Request (ClOrdID,OrigClOrdID) | Response (ClOrdID,OrigClOrdID) | ExecType | OrdStatus | OrderQty | CumQty | LeavesQty | LastQty | Comment |
|---|---|---|---|---|---|---|---|---|---|
| 1 | NewOrderSingle(A) | 10 | |||||||
| 2 | ExecutionReport(A) | PendingNew | PendingNew | 10 | 0 | 10 | |||
| 3 | ExecutionReport(A) | Rejected | Rejected | 10 | 0 | 10 | If order is rejected | ||
| 3 | ExecutionReport(A) | New | New | 10 | 0 | 10 | |||
| 4 | OrderCancelRequest(B,A) | ||||||||
| 5 | OrderCancelRejected(B,A) | New | 10 | 0 | 10 | If cancel is rejected | |||
| 5 | ExecutionReport(B,A) | PendingCancel | PendingCancel | 10 | 0 | 10 | |||
| 6 | OrderCancelRejected(B,A) | New | 10 | 0 | 10 | If cancel is rejected | |||
| 7 | ExecutionReport(B,A) | Canceled | Canceled | 10 | 0 | 0 |
Replace to increase quantity
| Time | Request (ClOrdID,OrigClOrdID) | Response (ClOrdID,OrigClOrdID) | ExecType | OrdStatus | OrderQty | CumQty | LeavesQty | LastQty | Comment |
|---|---|---|---|---|---|---|---|---|---|
| 1 | NewOrderSingle(A) | 10 | |||||||
| 2 | ExecutionReport(A) | PendingNew | PendingNew | 10 | 0 | 10 | |||
| 3 | ExecutionReport(A) | New | New | 10 | 0 | 10 | |||
| 4 | OrderCancel/ReplaceRequest(B,A) | 11 | |||||||
| 5 | OrderCancelRejected(B,A) | New | 10 | 0 | 10 | If replace is rejected | |||
| 5 | ExecutionReport(B,A) | PendingReplace | PendingReplace | 10 | 0 | 10 | |||
| 6 | OrderCancelRejected(B,A) | New | 10 | 0 | 10 | If replace is rejected | |||
| 6 | ExecutionReport(B,A) | Replaced | New | 11 | 0 | 0 | |||
| 7 | ExecutionReport(B) | Trade | PartiallyFilled | 11 | 1 | 10 | 1 |
Replace during fill
| Time | Request (ClOrdID,OrigClOrdID) | Response (ClOrdID,OrigClOrdID) | ExecType | OrdStatus | OrderQty | CumQty | LeavesQty | LastQty | Comment |
|---|---|---|---|---|---|---|---|---|---|
| 1 | NewOrderSingle(A) | 10 | |||||||
| 2 | ExecutionReport(A) | PendingNew | PendingNew | 10 | 0 | 10 | |||
| 3 | ExecutionReport(A) | New | New | 10 | 0 | 10 | |||
| 4 | OrderCancel/ReplaceRequest(B,A) | 8 | |||||||
| 5 | ExecutionReport(A) | Trade | PartiallyFilled | 10 | 1 | 9 | 1 | Fill before replace is received | |
| 6 | ExecutionReport(B,A) | PendingReplace | PendingReplace | 10 | 1 | 9 | |||
| 7 | ExecutionReport(A) | Trade | PendingReplace | 10 | 3 | 7 | 2 | Fill before replace is processed | |
| 8 | ExecutionReport(B,A) | Replaced | New | 8 | 3 | 5 | |||
| 9 | ExecutionReport(B) | Trade | Filled | 8 | 8 | 0 | 5 |
FIX example messages
Logon
8=FIX.4.4^A9=143^A35=A^A34=1^A49=CUSTOMER^A52=20220915-18:29:58.756^A56=Secure Digital^A95=44^A96=ZduZiNxyxS7_4UPDesOryd9KVEecg9LAqqTRR79Pp20=^A98=0^A108=300000^A141=Y^A554=Daniel^A10=248^ALogon response
8=FIX.4.4^A9=78^A35=A^A34=1^A49=Secure Digital^A52=20220915-18:29:58.765^A56=CUSTOMER^A98=0^A108=300000^A141=Y^A10=255^ASecurityList request
8=FIX.4.4^A9=88^A35=x^A34=3^A49=CUSTOMER^A52=20220930-13:28:16.451^A56=Secure Digital^A320=id-220929160342682-27^A559=4^A10=156^ASecurityList response
8=FIX.4.4^A9=243^A35=y^A34=3^A49=Secure Digital^A52=20220930-13:28:16.514^A56=CUSTOMER^A146=2^A55=ETH-USD^A48=2^A561=0.00000001^A562=0.00000001^A969=0.00001^A1140=1000.00^A55=BTC-USD^A48=24^A561=0.00000001^A562=0^A969=0.01^A1140=1000.00^A320=id-220929160342682-27^A322=1BQM22QR01G00^A560=0^A10=153^ANewOrderSingle
8=FIX.4.4^A9=147^A35=D^A34=2^A49=CUSTOMER^A52=20220915-18:30:01.335^A56=Secure Digital^A11=id-220912164936074-1152^A38=1^A40=2^A44=1630.123^A54=2^A55=ETH-USD^A59=1^A60=20220915-14:30:01^A10=228^AExecutionReport rejection
8=FIX.4.4^A9=366^A35=8^A34=2^A49=Secure Digital^A52=20220915-18:30:01.393^A56=CUSTOMER^A1=default^A6=0^A11=id-220912164936074-1152^A14=0^A17=ba22dbe1-cb33-4fcb-9613-921006afdebd^A37=94869628-b862-43e4-bd2d-be85e4295bd4^A38=1.00000000^A39=8^A40=2^A44=1630.123^A54=2^A55=ETH-USD^A58=Unable to submit market order - please try again later.^A59=1^A60=20220915-14:30:01.000^A103=0^A150=8^A151=1.00000000^A20030=N^A20032=A^A10=205^^AMarketDataSnapshot request
8=FIX.4.4^A9=186^A35=V^A34=2^A49=CUSTOMER_MD^A52=20220930-13:28:06.146^A56=Secure Digital^A262=id-220929160342682-26^A263=1^A264=0^A265=0^A1070=1^A146=1^A55=ETH-USD^A267=2^A269=0^A269=1^A20020=4^A20021=1^A20021=2^A20021=5^A20021=10^A10=226^AMarketDataSnapshot response
8=FIX.4.4^A9=608^A35=W^A34=2^A49=Secure Digital^A52=20220930-13:28:06.454^A56=CUSTOMER_MD^A55=ETH-USD^A262=id-220929160342682-26^A268=8^A269=0^A270=1320.43^A271=1.00000000^A272=20220930^A273=13:28:06.401^A269=0^A270=1320.43^A271=2.00000000^A272=20220930^A273=13:28:06.401^A269=0^A270=1320.43^A271=5.00000000^A272=20220930^A273=13:28:06.401^A269=0^A270=1320.43^A271=10.00000000^A272=20220930^A273=13:28:06.401^A269=1^A270=1323.42^A271=1.00000000^A272=20220930^A273=13:28:06.401^A269=1^A270=1323.42^A271=2.00000000^A272=20220930^A273=13:28:06.401^A269=1^A270=1323.42^A271=5.00000000^A272=20220930^A273=13:28:06.401^A269=1^A270=1323.42^A271=10.00000000^A272=20220930^A273=13:28:06.401^A10=247^ASDM Trading API PDF
Original SDM Trading API PDF provided for reference.
SDM Trading API PDF
Open the original SDM Trading API document.
Secure Digital FIX API PDF
Original Secure Digital FIX API PDF provided for reference.
Secure Digital FIX API PDF
Open the original Secure Digital FIX API document.
Source changelog
Version notes from both source PDFs.
| Version | Changes |
|---|---|
| Trading API v1.4.0 | Adds new REST API endpoint OHLCV |
| Trading API v1.3.0 | Adds new subscription BalanceTransaction Adds new command NewWithdrawRequest |
| Trading API v1.2.0 | Change TransactTime on QuoteRequest and <a href=#executionreport">ExecutionReport to be optional. Please note that this documentation change reflects existing behavior in the API. Change Currency on QuoteRequest to be required. Please note that this documentation change reflects existing behavior in the API. Add MinAmtIncrement field to Security. |
| Trading API v1.1.0 | Change MaximumSize for Security to be optional field. |
| FIX API v2.50 | V 2.50: Added description for Order Strategies |